|
Getting your Trinity Audio player ready...
|

In January, I wrote about Fifth Frame Brewing’s abrupt closure and the financial disputes that were already piling up before owner Jon Mervine posted the brewery’s farewell message.
In that Instagram post, Fifth Frame said the decision to close came with “heavy hearts” and was “an incredibly difficult” but “unavoidable” choice. The brewery thanked customers, employees and supporters across Rochester and beyond, while asking gift card holders to reach out and encouraging people to continue supporting local businesses and craft breweries.
At the time, only part of the situation was visible: a landlord dispute, a pending lawsuit from Crosby Hop Farm, and unanswered questions about what led one of Rochester’s most ambitious brewery concepts to close. Since then, additional court proceedings and state records have filled in more of the picture. The quantified claims and judgments in the cases and state records I reviewed total more than $444,000, before accounting for the landlord’s disputed claim for future lease damages. That total includes an $84,000 default judgment entered against Fifth Frame in Monroe County Supreme Court on July 31, after the state Workers’ Compensation Board found the brewery had failed to carry workers’ compensation insurance for more than a year. State records also show a separate $60,834 sales tax warrant against Fifth Frame, although nearly all of that amount has since been paid.
Quantified claims and judgments
The filings document the financial pressure Fifth Frame was under:
■ Five Star Bank: $169,528 claimed, plus interest
■ REO Holdings: $140,533 claimed, plus disputed future lease damages
■ American Express: $18,205 claimed
■ Crosby Hop Farm: $32,046 judgment
■ New York Workers’ Compensation Board: $84,000 default judgment
These figures do not represent a final accounting of Fifth Frame’s debts, and several remain disputed in court.
The brewery’s financial problems were not confined to the months immediately before Fifth Frame closed. The landlord’s lawsuit traces unpaid rent to 2023, while Crosby Hop Farm’s claims involved hops delivered in 2023 and 2024. By the time Fifth Frame announced its closure in January, multiple creditors were already pursuing the company.
The records also reveal something that was not publicly known when Fifth Frame closed: co-founders Mervine, Wade Reed and Jarred Foster were not Fifth Frame’s only owners, and two of its three best-known founders remained personally tied to a bank loan years after they had left the business. Neither Mervine nor his attorney responded to requests for comment for this story.
Before it carried the Fifth Frame name, the concept was known as Split Batch Brewing—a coffee roaster, breakfast spot and craft brewery proposed by three Rochester entrepreneurs who wanted to combine their separate areas of expertise into one business.
In 2015, Split Batch won the inaugural Retailent Rochester competition, earning one year of free rent at 155 St. Paul St. and other startup support.
Mervine brought brewing experience from Roc Brewing. Reed brought coffee expertise from Joe Bean Coffee Roasters. Foster brought culinary experience from Cure at the Rochester Public Market.
The concept eventually became Fifth Frame Brewing, which opened in 2017 with the same basic vision: a destination where customers could move from coffee and breakfast to beer and dinner under one roof.
“This is a cross-pollination of all of our passions,” Mervine said at the time.
To turn that concept into reality, Fifth Frame secured a loan from Five Star Bank in March 2017. Nearly a decade later, that same loan became the center of a dispute over who remained responsible for the debt.
The Five Star loan
Five Star Bank is pursuing the largest clearly quantified debt in the court filings. The lawsuit also puts the personal guarantees that helped Fifth Frame secure financing at the center of the dispute. In April, Five Star sued Fifth Frame Brewing and three personal guarantors: Mervine, Reed and Foster.
According to the complaint, Fifth Frame borrowed $591,200 from Five Star in March 2017 through a loan backed by the U.S. Small Business Administration. The loan was personally guaranteed by Mervine, Reed and Foster. The bank alleges the brewery defaulted after missing its October 2025 payment, prompting Five Star to accelerate the debt and demand immediate repayment of $169,528, plus interest accruing at more than $20 per day.
In Fifth Frame’s case, the personal guarantees became a point of contention years after the loan was signed—and after some of the people who guaranteed it were no longer involved in the company’s day-to-day operations.
A hidden ownership structure
The Five Star lawsuit became considerably more revealing after Foster responded. His answer and cross-claims include portions of Fifth Frame’s March 2017 operating agreement, providing the first public look at the brewery’s internal ownership structure.
Previous reporting identified Mervine, Reed and Foster as the founders behind Fifth Frame. The operating agreement shows they were not the company’s only owners, with minority investors also holding membership interests that are not identified in the court filings. It also details the members’ ownership interests, contributions and roles when the brewery launched.
The ownership structure outlined in the operating agreement was:

There is no accounting in the court filings for what the ownership structure looked like when the business closed.
According to Foster’s filing, he left Fifth Frame in August 2019 and had no further involvement in its operations. Reed also left the business years before it closed. Yet both remained personal guarantors on the SBA-backed loan they signed when Fifth Frame was getting started, according to Five Star’s lawsuit.
Foster’s dispute with Five Star is not over whether Fifth Frame owed the money. It is over whether he should still be responsible for it.
Foster says Five Star knew he had left the brewery and began the process of removing him as a guarantor in January 2020. According to his filing, the bank requested tax returns and financial statements and told him the release process was underway, pending approval from the SBA.
That release never happened.
Foster contends the process stalled, leaving him personally liable for the loan despite having no role in Fifth Frame’s operations since his departure. He is asking the court to prevent Five Star from enforcing his guarantee under the doctrine of equitable estoppel.
Foster has also filed cross-claims against Mervine and Reed seeking contribution, indemnification and damages for what he characterizes as breaches of fiduciary duty arising from the brewery’s continued borrowing and operations after his departure.
Five Star acknowledges that it never completed the guarantor-removal process or issued Foster a formal release. But the bank disputes Foster’s account of why. It contends the process stalled because Foster and/or Fifth Frame failed to provide documentation needed for a replacement guarantor.
The bank’s position is straightforward: No formal release was ever executed, so Foster remains liable under the guarantee.
Five Star is not the only party pursuing money from Fifth Frame.
The brewery ultimately vacated its St. Paul Street property without contesting the eviction. But leaving the building did not resolve its financial dispute with REO Holdings 155 LLC, the property’s owner.
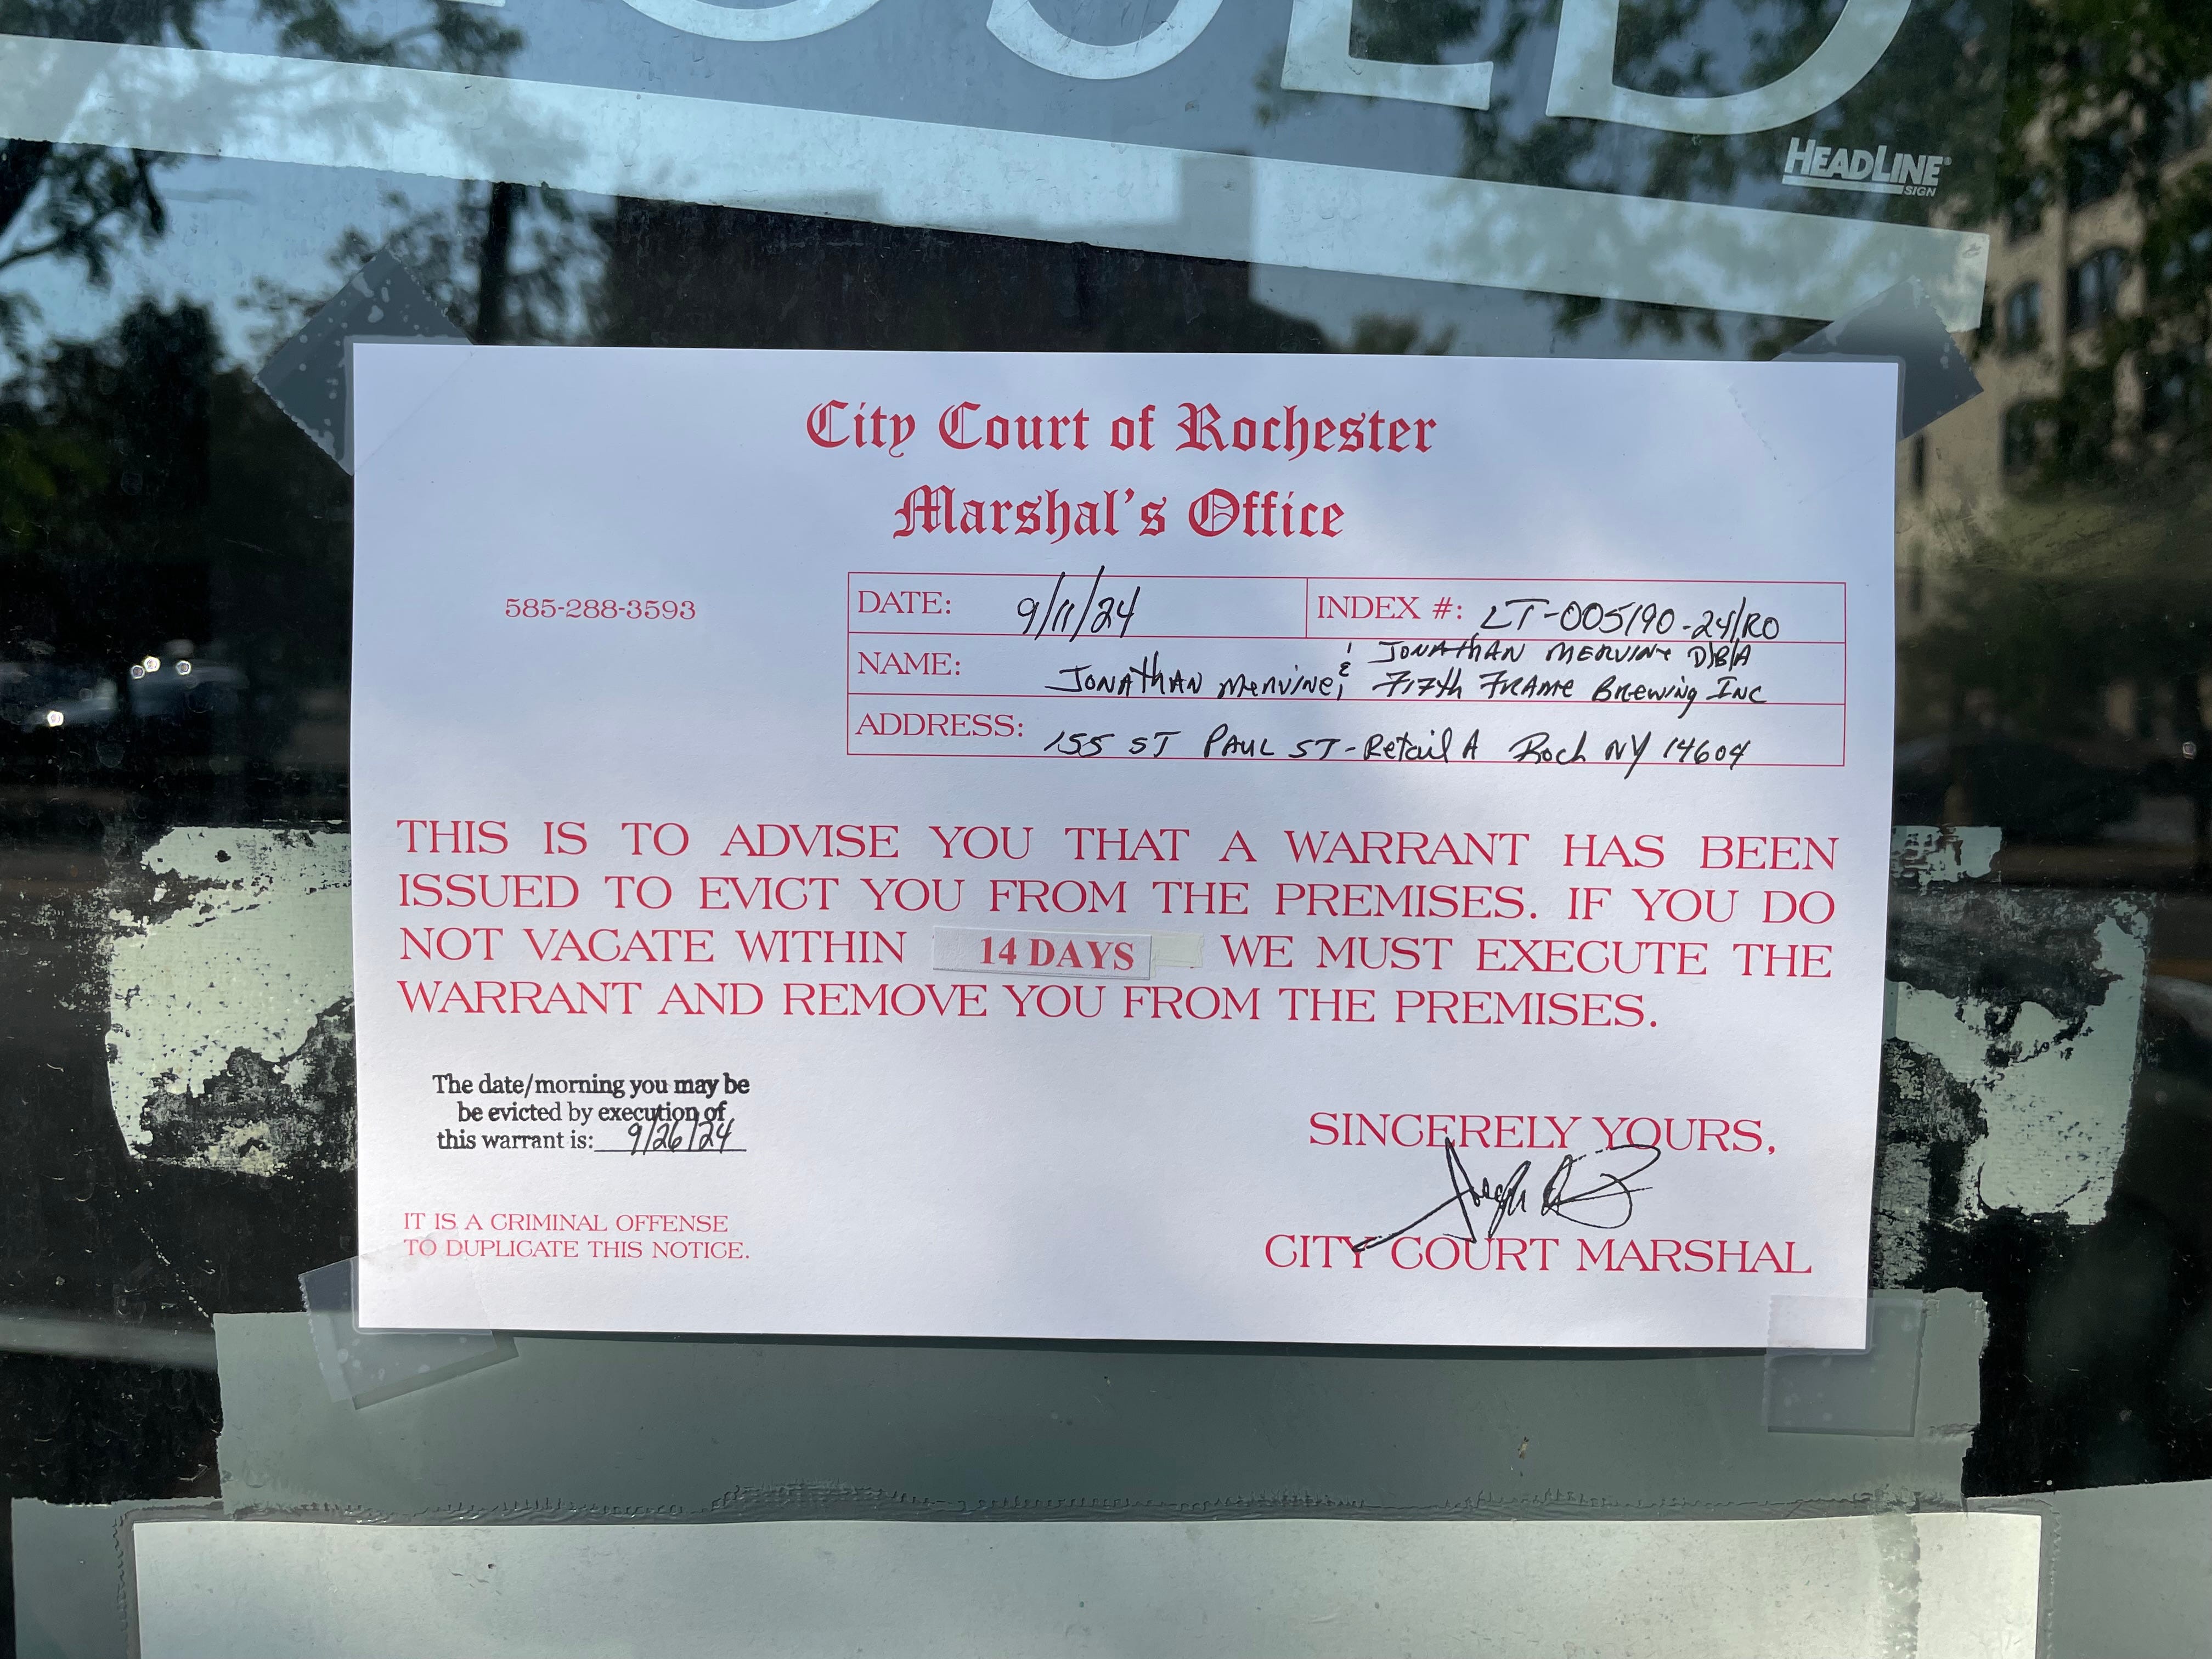
REO Holdings filed suit in December 2024 seeking $140,533 in unpaid rent, late charges and disputed equipment costs through early December, along with additional damages it says are owed through the remainder of Fifth Frame’s lease, which extends through May 2028.
The landlord also alleges Fifth Frame removed roughly $27,500 worth of fixtures and kitchen equipment when it vacated the property, including a six-burner oven, a three-group espresso machine, multiple coolers and sinks.
Mervine and Fifth Frame disputed the landlord’s claims in an answer filed in February through attorney David Panzarella. They asserted defenses including failure to mitigate damages, unclean hands, estoppel and accord and satisfaction, and filed counterclaims alleging that REO Holdings failed to provide the 30-day written notice to cure required under the lease before declaring a default.

Fifth Frame also claims the landlord retained trade fixtures and equipment the brewery surrendered under protest and was unjustly enriched by doing so. It is asking the court to dismiss the landlord’s claims and award damages in its favor.
Another lawsuit is considerably more straightforward. American Express National Bank sued Fifth Frame Brewing and Mervine personally in January, alleging the brewery defaulted on its Delta SkyMiles Reserve Business Card account. According to the complaint, the last payment of $585 was made in February 2025. By the time American Express filed suit, it claimed the balance had grown to $18,205.
Mervine denied he was in default and argued, among other things, that payments had not been properly credited and that service may have been defective. In May, American Express moved for summary judgment against both defendants. The motion is expected to be decided on written submissions later this summer.
The Crosby Hop Farm case, which I described as a pending default judgment in January, has since been formally entered as a judgment. Judge Joseph Waldorf signed the judgment Dec. 30, 2025, and the Monroe County clerk entered it Jan. 2.
The final tally came to $32,046, including $27,698 in principal, $2,493 in interest, $1,215 in attorneys’ fees and $640 in costs and disbursements. Unlike the American Express and Five Star Bank matters, Fifth Frame never answered the lawsuit, allowing the judgment to be entered by default.
The court cases are not the only public evidence of Fifth Frame’s financial obligations. New York records show the Department of Taxation and Finance docketed a $60,834 sales-tax warrant against Fifth Frame Brewing on May 20. The state database lists the current balance at $22.40, indicating that nearly all of the warrant amount has since been satisfied.
The Workers’ Compensation Board has also gone to judgment against Fifth Frame. Board records show Fifth Frame failed to carry workers’ compensation insurance from April 30, 2025, through June 23, 2026. The Workers’ Compensation Board assessed the brewery $84,000, and said the penalty remained unpaid more than 30 days after demand. The board filed affirmations of non-payment and regularity with the Monroe County clerk on July 30, and a judgment for the full $84,000 was entered the following day.
State UCC filings show at least two additional parties with secured claims against Fifth Frame’s assets that have not been reported previously.
A UCC filing—short for Uniform Commercial Code financing statement—is a public record a lender files when it lends money secured by a business’s assets, like equipment, inventory or accounts receivable. It doesn’t mean the business is in trouble or in default. It’s a routine, legally required step that gives the lender priority to claim those specific assets over other creditors if the borrower doesn’t pay. Filing one is standard practice any time a business takes out a secured loan.
In June 2020, Fifth Frame took out a loan directly from the SBA, secured by a broad lien on the company’s inventory, equipment, accounts and other business assets. The filing does not state a loan amount. The timing and structure—a direct SBA loan rather than a bank loan with an SBA guarantee—are consistent with the federal government’s COVID-era Economic Injury Disaster Loan program, though Fifth Frame’s records do not specify which program the loan came from.
Records supplied by ProPublica show Fifth Frame separately received two Paycheck Protection Program loans in 2020 and 2021, totaling roughly $92,000, both of which were fully forgiven; PPP loans did not require collateral, which further points to the June 2020 lien reflecting a different, disaster-loan-based debt. A continuation filing in June 2025 shows the lien was still active roughly seven months before the brewery announced its closure.
A separate UCC filing is dated Jan. 12, 2026, just days after Fifth Frame announced its closure. WebBank, a Utah-based bank, claimed a security interest in the brewery’s accounts receivable and payment-card revenue. As with the SBA filing, the amount of the loan is not disclosed in the public record. It is not clear whether the lien reflects new financing extended around the time of the closure or the continuation of an earlier lending relationship.
Neither filing indicates whether the underlying loans are in default, and unlike the court judgments detailed above, UCC filings do not by themselves establish that money is owed—only that a lender has a legal claim on specific assets if it is.
The records do not provide a single answer for why Fifth Frame closed. The brewery has not publicly detailed the financial circumstances behind its decision, beyond calling the closure “unavoidable.”
But they do show the breadth of the financial problems surrounding the brewery: unpaid suppliers and other creditors; a landlord seeking rent and damages; a credit-card balance; tax liabilities; a lapse in required workers’ compensation coverage; and a bank pursuing repayment on a loan that dates to the brewery’s launch.
The full picture of Fifth Frame’s finances may never be knowable from public records alone. What those records show is that the brewery’s January closure came after years of accumulating obligations.
What looked from the outside like an abrupt closure was, in light of the court and state records, the final chapter of a financial unraveling that had been underway for years.
Will Cleveland is a Rochester Beacon contributing writer.
The Beacon welcomes comments and letters from readers who adhere to our comment policy including use of their full, real name. See “Leave a Reply” below to comment on this post. Comments of a general nature may be submitted to the Letters page by emailing [email protected].
Is it just me, or has Five Star Bank had a shaky pattern of loans associated with area microbreweries? K2, Fifth Frame — are there others?
Not clear why this business’ failure requires such a lengthy re-telling. Or any re-telling for that matter. Some businesses close due to managerial incompetence. Some because of naivete. And probably the most simply because of the lack of a viable business case. What makes yet another closing of yet another brewery special? The market was long ago saturated.